Knowledge Base · Inventory and Manufacturing
Applies to: All Supported Versions | Platform: Desktop & Cloud
Understanding how inventory costs are calculated is essential for accurate financial reporting and informed business decisions. Different inventory costing methods can significantly impact your cost of goods sold (COGS), gross profit, and taxable income.
This article provides an overview of the three inventory costing methods used in Connected:
- First-In First-Out (FIFO)
- Weighted Average
- Specific Costing (extension of FIFO for Lot/Serial Controlled items only)
ARTICLE CONTENTS
- FIFO (First In First Out)
- Weighted Average
- Specific Costing (FIFO Extension for Lot/Serial Control)
- Costing Example
- Related Articles
1. FIFO (First In First Out)
FIFO (First-In, First-Out) is the default inventory costing method in Connected. Under this approach, inventory is costed and depleted in the exact order it was received — meaning the oldest costs are applied first to outgoing items. This method closely mirrors the natural flow of inventory for many businesses, especially those handling perishable or time-sensitive goods.
FIFO provides a more precise view of your current inventory value, since it avoids cost blending and instead reflects actual purchase costs.
PROS
|
CONS
|
2. Weighted Average
The Weighted Average costing method blends the total cost of inventory with the total quantity available, resulting in a single "Average Cost" that is applied to all units. Rather than tracking the cost of individual items, this method smooths out cost variations by calculating an average every time inventory is received.
This method is best suited for businesses where inventory costs remain relatively stable over time.
PROS
|
CONS
|
3. Specific Costing (FIFO Extension for Lot/Serial Control)
Specific Costing is used exclusively for inventory items tracked by Lot or Serial numbers, allowing each unit to retain its exact purchase cost. While it follows the same structure as FIFO, it differs by letting specific items (and cost) be chosen for each transaction (Sales/Movement).
This method is ideal for high-value or regulated inventory where precise cost tracking is essential. It provides maximum transparency and control, especially useful when managing returns, warranties, or compliance requirements.
PROS
|
CONS
|
4. Costing Example
The following is a costing example that shows the movement in and out of inventory, using the different costing methods. In each case, the total cost on the invoice is much different, depending on the method used.
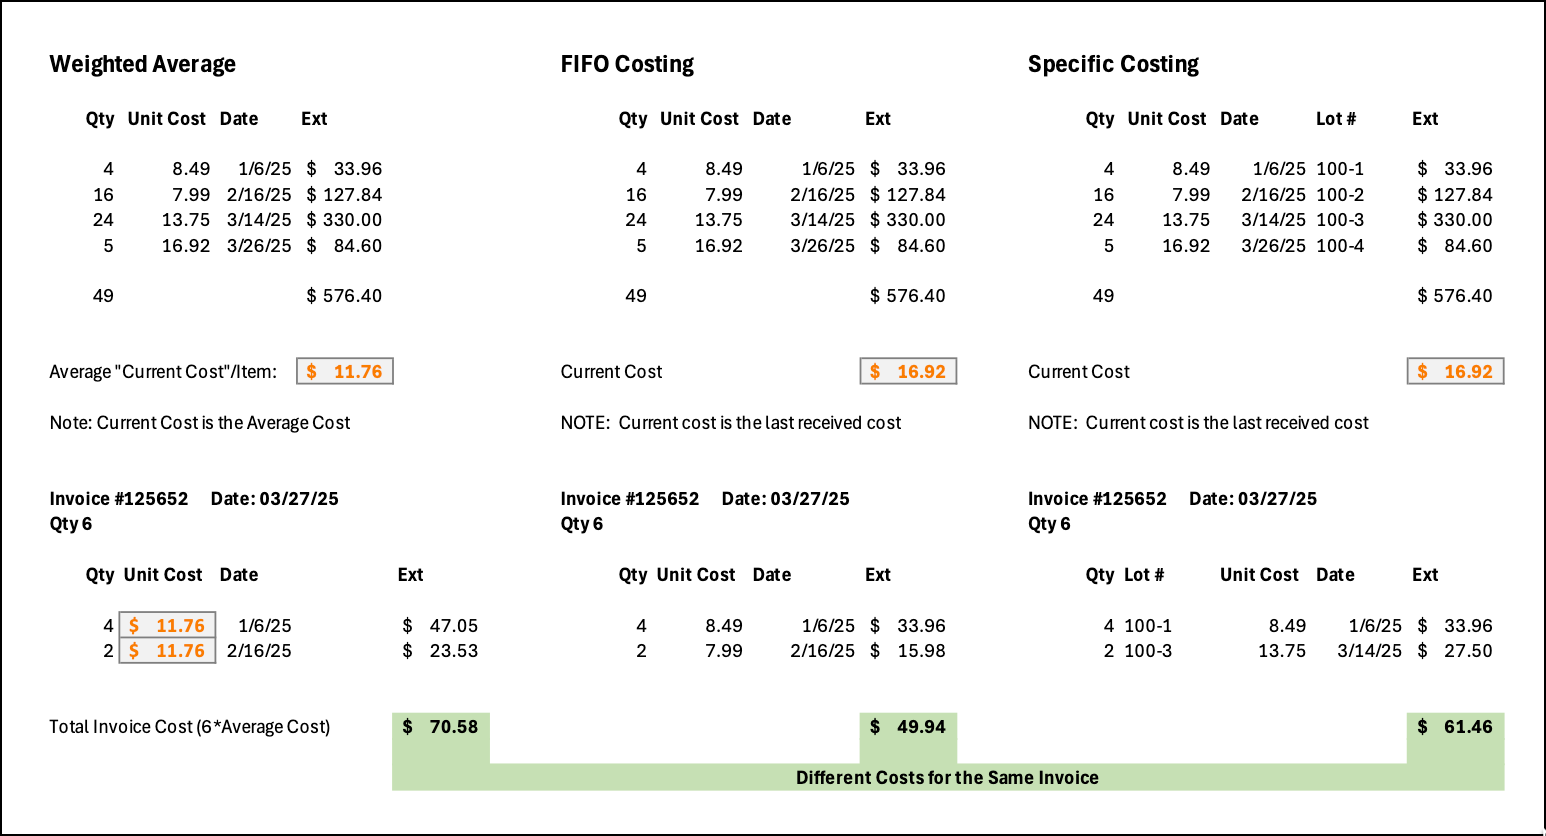
Inventory Received - Same Inventory Received with Different Costing Method Application Shown Below in the Invoice #125652 example
| Qty | Unit Cost | Date | Lot # (Specific Costing Only) | Ext |
|---|---|---|---|---|
| 4 | 8.49 | 1/6/25 | 100-1 | $33.96 |
| 16 | 7.99 | 2/16/25 | 100-2 | $127.84 |
| 24 | 13.75 | 3/14/25 | 100-3 | $330.00 |
| 5 | 16.92 | 3/26/25 | 100-4 | $84.60 |
| 49 | $576.40 |
Invoice #125652 | Date: 03/27/25 | Qty 6
| Method | Current Cost | Units Costed on the Invoice | Total Invoice Cost |
|---|---|---|---|
| Weighted Average | $11.76 Current Cost is the Average Cost | 4 × $11.76 = $47.05 2 × $11.76 = $23.53 | $70.58 |
| FIFO | $16.92 Current cost is the last received cost | 4 × $8.49 (1/6/25) = $33.96 2 × $7.99 (2/16/25) = $15.98 | $49.94 |
| Specific Costing | $16.92 Current cost is the last received cost | 4 × $8.49 (Lot 100-1, 1/6/25) = $33.96 2 × $13.75 (Lot 100-3, 3/14/25) = $27.50 | $61.46 |
| Different Costs for the Same Invoice | |||
5. Related Articles
Was this article helpful?
That’s Great!
Thank you for your feedback
Sorry! We couldn't be helpful
Thank you for your feedback
Feedback sent
We appreciate your effort and will try to fix the article